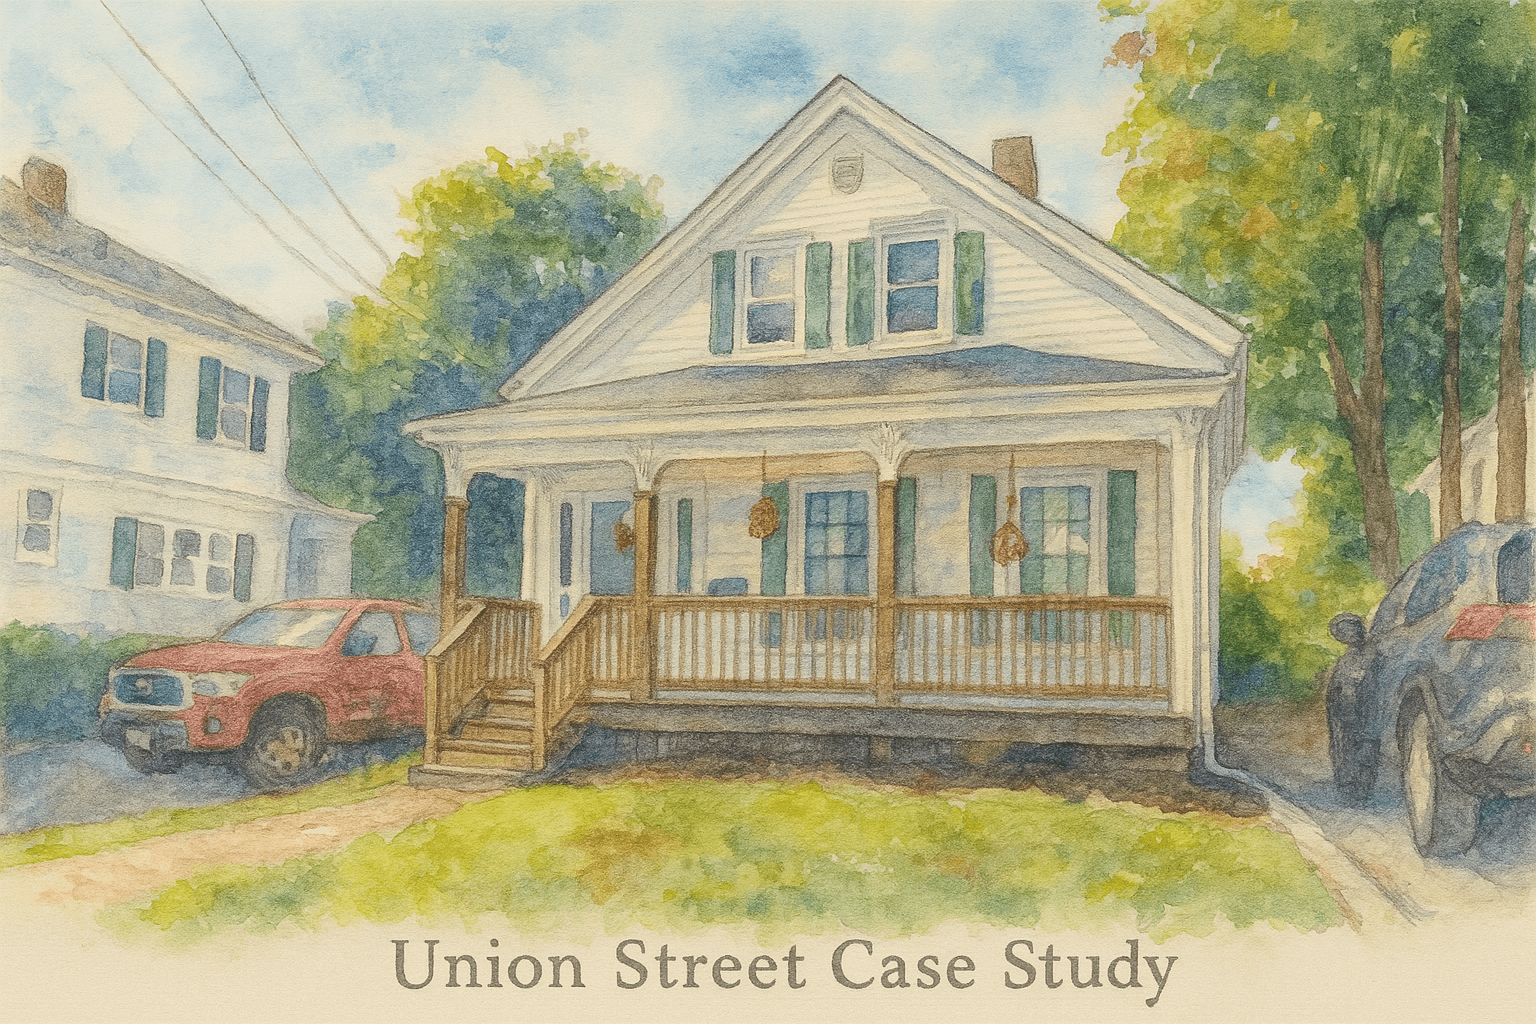
Taunton, Massachusetts · Acquired September 2022 · Sold to a charitable trust 2024
Most recovery housing case studies are about buying a distressed property, fixing it, and holding it. This one is the opposite. Union Street was already a well-run sober home when we found it, and the best move was not to hold it forever. It was to exit into a charitable structure that preserved the home, promoted a resident into ownership of his own operating business, and produced a six-figure tax deduction for the developer.
The developer put roughly $500,000 into the property and sold it to a charitable real estate trust for $720,000 against a $1,000,000 appraised value. The $220,000 cash gain was fully offset by the $280,000 charitable deduction created by the bargain sale. Here is how the deal came together, and what it takes to repeat it.
Finding the Deal: A Legacy in Transition
The opportunity began with an email to our community team. A longtime operator in Taunton was preparing for retirement and looking to sell a home that had served the recovery community for nearly a decade. He was not simply looking for a buyer. He was looking for someone who would keep the home doing what it had been doing.
This was not a fixer-upper. The home was operational, stable, and well-regarded locally, which meant it would not sit on the market. On behalf of one of our local developer partners, we moved quickly to negotiate a purchase price that reflected both the property’s active use and the seller’s priority of continuity.
The deal closed in September 2022 with twelve-month bridge financing at a sub-10 percent rate, an efficient, low-risk way to secure the asset while the long-term strategy was planned. Bridge debt was the right instrument here precisely because the exit was not yet defined: it bought time without locking the developer into a thirty-year position on a property she did not intend to hold.
Why an Operating Sober Home Is an Underrated Acquisition
Developers gravitate toward distressed property because the value-add is visible: buy low, renovate, lease, refinance. An already-operating recovery home offers a different and often better proposition.
- The demand is proven, not projected. A home with a decade of occupancy history has referral relationships, a known reputation with local providers, and a waitlist. You are not underwriting a forecast.
- There is no construction risk. No permits, no contractor schedule, no lease-up gap while renovations run long.
- Income starts on day one. Bridge or acquisition debt is serviced by rent immediately rather than out of pocket for six months.
- The seller often cares about more than price. Retiring operators want continuity, which can widen the terms available to a buyer who credibly offers it.
What you give up is the forced appreciation a renovation creates. That trade only makes sense when your return comes from somewhere else, which, in this deal, it did.
Cultivating Leadership: From House Mentor to Operator
At the time of purchase there was no operator committed for the next phase. To hold continuity, VSL stepped in to manage the home on a contract basis. That is a rare move for us, and one we made because the alternative was letting a working home go dark.
During that stewardship period we met someone remarkable. A resident who had taken on a House Mentor role stood out, not because of his resume but because of his consistency, care, and presence. His past included incarceration and criminal charges. His future looked different.
We invited him into our Leadership Development Program, which pairs structured coaching with gradually increasing responsibility. Over the following year he moved from resident to contract operator, and then to leaseholder with a signed lease and a business of his own.
Today he runs multiple recovery homes across Taunton and New Bedford. Union Street was not a stop on his journey. It was the turning point.
That progression is also what made the exit possible. A charitable trust cannot take on a home with no operator; the asset only had value to the trust because there was a credible, invested leaseholder already running it.
The Charitable Sale: Structuring a Purpose-Driven Exit
Unlike investors who optimize for long-term cash flow, this developer had a different objective: pairing impact with deliberate tax planning. From the start we worked with her CPA to model a charitable sale, sometimes called a bargain sale.
How a Bargain Sale Works
In a bargain sale, a property is sold to a qualified charitable organization for less than its appraised fair market value. The transaction splits into two parts. The portion you receive in cash is a sale, taxed on the gain allocable to it. The difference between fair market value and the sale price is treated as a charitable contribution, which generates a deduction. Structured well, the deduction can offset the gain entirely.
Two things make or break it: a defensible qualified appraisal establishing fair market value, and a genuine charitable recipient. Neither is a formality.
| Metric | Amount | Notes |
|---|---|---|
| Purchase price | $450,000 | September 2022 |
| Improvements and carrying costs | $50,000 | Total basis of $500,000 |
| Appraised fair market value | $1,000,000 | Stabilized valuation |
| Sale price to charity | $720,000 | Structured bargain sale |
| Cash gain | $220,000 | Sale price less total basis |
| Charitable deduction | $280,000 | Fair market value less sale price |
| Net taxable gain | $0 | Offset by the deduction |
The Charitable Real Estate Trust
We helped establish a charitable real estate trust, a 501(c)(3)-affiliated vehicle built to hold recovery homes for long-term community use. With the operator in place and the lease signed, the asset was sold to the trust at a discount to appraised value.
The trust structure is the part most developers have not considered. A recovery home held by a mission-aligned nonprofit is insulated from the pressure that eventually pushes most rental property back onto the market: it will not be sold out from under the operator when interest rates move or an estate is settled. For a retiring seller worried about legacy, and for a new operator building a business, that permanence is the point.
What Each Party Got
- The developer realized $220,000 in profit, offset to zero taxable gain by the charitable deduction.
- The charitable trust acquired a stabilized, leased home well below fair market value.
- The operator got a long-term lease, a stable landlord, and the foundation of the portfolio he runs today.
- The retiring seller got the continuity he had asked for in the first place.
This case study is educational and is not tax, legal, or investment advice. Bargain sale treatment depends on a qualified appraisal, the recipient’s charitable status, your deduction limits, and facts specific to your situation. Figures reflect this transaction only. Work with your own CPA and counsel before structuring anything similar.

This deal is one of the case studies in How to Finance Recovery Housing, Book Two of the three-part series by Dr. Hunter T. Foote, alongside How to Buy a Sober House and How to Upfit Residential Properties.
Why This Works: Short-Term Ownership, Long-Term Impact
The Union Street deal shows that you do not have to hold forever to create lasting impact. With the right partnerships and planning, developers can:
- Earn real returns on modest capital investments, without a renovation cycle.
- Exit tax-efficiently using a bargain sale and the charitable deduction it generates.
- Empower new leaders and protect housing continuity for the residents already living there.
- Build a philanthropic legacy through giving structures that outlast a single ownership period.
It is worth being clear about what makes this replicable and what does not. The tax outcome is available to anyone with a qualified appraisal, a real charitable recipient, and enough deduction capacity to absorb the contribution. The rest (a stabilized home, a trained operator ready to take a lease, and a nonprofit prepared to hold recovery real estate) is the part that takes two years and a network to assemble.
Key Takeaways for Mission-Aligned Developers
- Established homes are undervalued assets. You skip the renovation risk and buy proven occupancy, referral relationships, and reputation.
- Bridge debt fits an undefined exit. Short-term financing kept the developer’s options open while the operator and the trust came together.
- Operator development is deal infrastructure. The exit only worked because someone was ready to hold the lease. Leadership pipelines are not a soft benefit; they are what makes the asset transferable.
- Short-term strategies can create long-term impact when paired with nonprofit trusts and deliberate tax planning.
- Charitable sales unlock value while supporting your values. With the right structure, part of your gain becomes a gift, and the deduction can offset the rest.
- Bring the CPA in early. This was modeled with the developer’s accountant from the beginning, not reverse-engineered at closing.
Exploring a Tax-Smart Exit of Your Own
If you are a real estate developer, CPA, or donor-advised fund manager looking at tax-smart exits through recovery housing, the structure above is repeatable, but only with a stabilized home, a credible operator, and a qualified charitable recipient in place before you start. VSL helps assemble all three. Start the conversation with our team and we will walk through what your property and timeline would support.
What would your property do?
Start with the numbers, or start the conversation.
Run a custom income projectionFree calculator: see the numbers for your specific property. Get the investor book seriesDr. Foote’s guides to buying, financing, and upfitting recovery housing. Talk to VSL about your propertyExplore leasing to a vetted operator, no operating required.
Or call (844) 762-3747, weekdays 8a to 5p.
Frequently Asked Questions About Charitable Exits in Recovery Housing
What is a bargain sale of real estate?
A bargain sale is a sale of property to a qualified charity for less than appraised fair market value. It splits into two parts: the cash portion is a taxable sale, and the discount below fair market value is treated as a charitable contribution that generates a deduction.
How did the developer pay no tax on a $220,000 gain?
The $280,000 charitable deduction created by selling at $720,000 against a $1,000,000 appraisal exceeded the $220,000 gain over her $500,000 basis. Whether a deduction fully offsets a gain depends on your own deduction limits and other income, so model it with a CPA.
Do I need a qualified appraisal for a bargain sale?
Yes. The charitable contribution portion is measured against appraised fair market value, so a defensible qualified appraisal is the foundation of the whole structure. Without it there is no supportable deduction.
What is a charitable real estate trust?
In this deal it was a 501(c)(3)-affiliated vehicle created to hold recovery homes for long-term community use. Because the trust is mission-driven rather than return-driven, the home is insulated from being sold out from under its operator when market conditions change.
Can I sell a sober living home to a charity if it has no operator?
It is much harder. A charitable holder is acquiring an income-producing, leased asset. Without a credible operator under lease, there is no stabilized income to appraise and no continuity for the trust to preserve, which undermines both the valuation and the mission case.
How long did this deal take from purchase to exit?
The property was acquired in September 2022 with twelve-month bridge financing. VSL managed the home on contract while a House Mentor was developed into a contract operator and then a leaseholder, and the charitable sale followed once the lease was in place.
Research & Sources
- Foote, H. T. (2026). Vanderburgh Sober Living Operating Climate Index, 2026 edition. Vanderburgh Sober Living. https://www.vanderburghhouse.com/research/operating-climate-index-2026/
- Code of Federal Regulations tit. 26, § 1.1011-2. (n.d.). Bargain sale to a charitable organization. Legal Information Institute, Cornell Law School. https://www.law.cornell.edu/cfr/text/26/1.1011-2
- Internal Revenue Service. (2025a). Publication 526: Charitable contributions. https://www.irs.gov/publications/p526
- Internal Revenue Service. (2025b). Publication 561: Determining the value of donated property. https://www.irs.gov/publications/p561
- Massachusetts Alliance for Sober Housing. (n.d.). MA Alliance for Sober Housing. https://mashsoberhousing.org/
- Massachusetts General Laws ch. 17, § 18A. (n.d.). Voluntary training and accreditation program for operators of alcohol and drug free housing. https://malegislature.gov/Laws/GeneralLaws/PartI/TitleII/Chapter17/Section18A
- United States Code tit. 26, § 170. (n.d.). Charitable, etc., contributions and gifts. Legal Information Institute, Cornell Law School. https://www.law.cornell.edu/uscode/text/26/170